by admin | Jun 19, 2026 | credit footprint, credit reference, expat, Expat mortgages, Mortgage rates, Re-mortgage, Switch mortgages, UK mortgage, UK property
The Silent -17% UK Property Crash: Why Waiting Could Cost You
While many investors are still waiting for a market correction, inflation-adjusted house prices have already fallen 17.4% since 2022. Here’s why savvy investors are using leverage to turn today’s market into tomorrow’s wealth.
Most investors are still waiting for a property crash. The reality? It may already have happened. When adjusted for inflation, UK property prices have fallen by more than 17% since their 2022 peak. While the headlines focus on nominal house prices, the real story is that inflation has quietly reduced property values in real terms without the panic, forced sales, and economic damage that normally accompany a traditional crash.
This isn’t a statistic I’ve invented. The figure comes from a recent episode of The Property Podcast, where the hosts analysed Nationwide’s inflation-adjusted house price data rather than the headline prices typically reported in the media.
Looking at Nationwide’s real house price series, they highlighted that UK property values have fallen by approximately 17.4% in real terms since the first quarter of 2022.
You can listen to the episode here:
https://open.spotify.com/episode/5RPguq8fhRcybdML81OGY0?si=98OP1fCxQ2uDy3sgX_yZ9w
The key point is that most property commentary focuses on nominal prices-the figures you see in estate agent windows and newspaper headlines. However, when inflation is taken into account, the picture looks very different. While prices have appeared relatively stable, inflation has quietly reduced property values in real terms, creating what the podcast describes as a “silent property crash”. And that’s creating an opportunity that many investors are missing.
History shows that wealth is rarely built when everyone is excited about property. It’s built during periods like this-when sentiment is low, media attention has moved elsewhere, and most people are sitting on the sidelines waiting for certainty. The investors who move first are often the ones who benefit most when confidence returns.
Ask about our finance and property partnerships in the North of England!!
The Power of Leverage
The real lesson isn’t simply that property is cheaper than many people realise. t’s that leverage amplifies the opportunity. Many expats hold substantial cash reserves while waiting for “the perfect time” to invest. Unfortunately, inflation doesn’t wait. Every year, cash loses purchasing power while asset owners continue building wealth.
A Mortgage changes the equation.
Instead of using all your capital to buy one property outright, leverage allows you to control multiple assets with the same money. Inflation gradually erodes the real value of the debt, while rents and property values have historically risen over the long term. This creates a powerful flywheel effect.
A Real-Life Example
Take Ahmed, an expat based in Qatar. Rather than leaving equity trapped in his main residence, he’s raising funds from his home and using them as deposits to build a UK property portfolio through a limited company. His plan is to purchase three buy-to-let properties in the North East at approximately £150,000 each.
Total property value: £450,000 Using mortgage finance, Ahmed only needs to contribute around approx £90,000 in deposits while controlling nearly half a million pounds worth of assets.
If property values grow by a conservative 5% per year over the next five years, here’s what happens:
- Portfolio value today: £450,000
- Portfolio value after 5 years: £574,000
- Capital growth: £124,000
Before considering a single pound of rental profit, the capital growth alone exceeds Ahmed’s original £90,000 investment.
Now let’s look at the rental income.
- Each property starts at £850 per month, generating:
- Year 1 rental income: £30,600 per year
- Year 5 rental income (assuming 5% annual rental growth): £39,000 per year
That’s an increase of more than £8,000 per year in rental income alone. By year five, Ahmed could be sitting on a portfolio worth more than half a million pounds, producing almost £40,000 a year in gross rental income, all from an initial £90,000 equity investment.
That is the power of a mortgage (leverage).
The Cost of Waiting
Five years from now, investors may look back at today’s market and wonder why more people weren’t buying. The biggest risk may not be buying too early. It may be spending years waiting while inflation quietly erodes cash and other investors continue building portfolios, equity, and income streams. The opportunity isn’t when everyone is talking about property. The opportunity is usually before they start.
Key Takeaway
Inflation quietly reduces the value of debt while supporting long-term rental growth.
Investors who understand leverage can use this to their advantage by controlling larger assets with less capital and allowing time, inflation, and compounding to do the heavy lifting.
The biggest risk in today’s market may not be buying too early.
It may be spending the next five years waiting while others continue building assets, equity, and income streams.
As an expat you may be unsure what might be possible or what your next move should be and we are on hand to help explore the options available to you.
Book a call here
Market Updates
- Bank Of England keep rates at 3.75% – If you waiting for rates to fall, you may be waiting some-time as the BOE balances inflation and a weak economy. read it here.
- UK regulator plans for easier mortgages… but could that spike house prices? read it here.
- No Surprises – UK rental market demand is up ! – this RICS report gives comfort to those about to jump into landlord property investing… read it here.
- Deal of the Week: A New 90% Expat residential mortgage deal is to be launched next week, increasing the competition for those Expats who are first time buyers & there are still some exceptional deals out there for expats. Enquire now
Next Steps…
Book a Free Discovery call here & if your not sure what a discovery call is all about Ive made a series of videos on what to expect here.
A Great way to get frequent updates, hints & tips and insider industry knowledge of the complex / expat mortgage market is to join our YouTube channel here.
Our Quick 60sec Quote page allows you to obtain the latest rates to be expected and you can request a specific quote by sending an email to info@mymotgagedeal.co.uk
by admin | May 29, 2026 | Uncategorized
How the BRR Strategy Can Turn £100,000 Into a Repeatable Property Investment Model
One of the most effective ways to build a UK buy-to-let portfolio is through the BRR strategy: Buy, Refurbish, Refinance. Done well, it allows you to recycle your capital, grow your portfolio faster, and improve your long-term return on investment.
Here’s a simple example.
Let’s say you start with £100,000 cash. You buy a property for £80,000, then invest £20,000 refurbishing it—updating kitchens or bathrooms, decorating, improving energy efficiency, or adding value through layout changes.
Your total investment is now £100,000.
We have such opportunities right now through our partnerships in the North of England!!
Once the work is complete, the property is revalued at £120,000. At that point, you refinance onto a buy-to-let mortgage at 80% loan-to-value, allowing you to borrow £96,000.
That means you pull £96,000 back out, leaving only £4,000 of your own money tied up in the property.
The key point? The property still produces income.
If the unit nets £350–£400 per month after mortgage payments and core costs, that gives you £4,200 to £4,800 profit per year.
When you compare that to the £4,000 of your own money left in the deal, the numbers become powerful:
- £4,200 annual profit = 105% return on cash left in
- £4,800 annual profit = 120% return on cash left in
That’s what investors mean by cash-on-cash return—and why BRR is so attractive.
The long-term goal with any investment property is often called “return on infinity”: owning an asset that still produces monthly profit while having little or none of your own capital left in it.
In many cases, the first refinance gets most of your money back. Then after 3–5 years, natural market appreciation, rental growth, and mortgage balance reduction can create another refinancing opportunity—often releasing the remaining cash still tied up.
At that stage, you may effectively have none of your original money left in the property, but it continues generating income and building equity.
That’s how BRR can become repeatable.
Buy right. Add value. Refinance. Recycle capital. Then repeat again with the next opportunity.
- Over time, one well-executed deal can become the foundation for a growing portfolio that compounds both income and wealth..
As an expat you may be unsure what might be possible or what your next move should be and we are on hand to help explore the options available to you.
Book a call here
Market Updates
- UK landlords exit the market – around 700 former rental properties are listed everyday in the UK, for sale, shrinking the rental market.. is this an opportunity for more committed landlords ? read it here.
- Halifax latest house price data… makes interesting reading for those thinking the property values are dropping. read the report here.
- The Boring way to Property Wealth – property is not get rich quick, its actually quite boring, but effective … watch it here.
- Deal of the Week: Expat residential mortgages still available @ 4.49% 2 Yr Tracker with No ERCs there are still some exceptional deals out there for expats. Enquire now
Next Steps…
Book a Free Discovery call here & if your not sure what a discovery call is all about Ive made a series of videos on what to expect here.
A Great way to get frequent updates, hints & tips and insider industry knowledge of the complex / expat mortgage market is to join our YouTube channel here.
Our Quick 60sec Quote page allows you to obtain the latest rates to be expected and you can request a specific quote by sending an email to info@mymotgagedeal.co.uk
by admin | Apr 24, 2026 | Uncategorized
From Dubai to Devon: Self -Build Your UK Dream Home with 80% LTV
For many UK expats, the dream of building a bespoke family home or a high-spec “returner” residence often feels out of reach due to the massive upfront capital typically required. However, a specialized Expat Residential Self-Build deal is currently disrupting the market by allowing Brits residing in over 160+ countries to leverage the final value of their project rather than just their current savings.
The Power of 80% GDV Lending
Unlike standard mortgages that look at what a property is worth now, this product focuses on the Gross Development Value (GDV)—the estimated market value of the home once it is finished.
The strategy works through a series of “stage releases” designed to keep your cash flow fluid:
- Stage 1: Buy the Plot or Refurb project : You can borrow up to 80% of the Plot or the current value of a property if you are doing a major refurbishment.
- Subsequent Stages: As you reach key milestones—such as foundations, wind-and-watertight, and first fix—you can draw down 80% of the build costs for that specific phase.
- The “Top-Up” Finale: In the final stages, as the property nears completion and its value “uplifts,” significantly there is an opportunity to top up your borrowing to 80% of the final end value.
Can You Really “Fully Fund” the Build?
Yes, if the project is priced & structured correctly. Careful consideration should be given to Re-furbs versus straight forward ground up developments, as complications in refurbs can make costs spiral. Ultimately self-building often creates significant equity, the final 80% of the GDV can then cover the remaining build costs and even reimburse some or all of your initial land deposit.
Key Requirements for Expats
While this product is available to UK expats resident in over 160+ countries, lenders typically require:
- Professional Oversight: A UK-based project manager, architect, or quantity surveyor to monitor the build.
- Income Verification: Evidence of your foreign income (which can be more complex than UK PAYE).
- Direct-to-Bank Payments: Funds are often released into a UK bank account following a successful valuation of each stage.
As an expat you may be unsure what might be possible or what your next move should be and we are on hand to help explore the options available to you.
Book a call here
Market Updates
- High St Lenders reducing rates – due to softening swap rates, the mortgage deals look to be improving… for now at least! read it here.
- Property market ..new seller asking prices rise by 0.8% but is it still a buyers market? read the report here.
- Energy prices linked to property ? – what happens to the property market when energy prices rise watch it here.
- Deal of the Week: Expat residential mortgages still available @ 4.45% 2 Yr discount there are still some exceptional deals out there for expats. Enquire now
Next Steps…
Book a Free Discovery call here & if your not sure what a discovery call is all about Ive made a series of videos on what to expect here.
A Great way to get frequent updates, hints & tips and insider industry knowledge of the complex / expat mortgage market is to join our YouTube channel here.
Our Quick 60sec Quote page allows you to obtain the latest rates to be expected and you can request a specific quote by sending an email to info@mymotgagedeal.co.uk
by admin | Apr 10, 2026 | credit footprint, Expat mortgages, Mortgage rates, Re-mortgage, Releasing cash, UK mortgage
Fixed Deals rise… but don’t Ignore Expat Discount deals!
Recent instability in the Middle East is having a direct knock-on effect on UK mortgage pricing. Although the conflict is geographically far from the UK , it affects global oil and gas prices, which in turn push inflation expectations higher.
When inflation fears rise, UK gilt yields and swap rates usually rise too — and these are the key benchmarks lenders use to price fixed-rate mortgages. That is why many UK lenders have recently increased fixed mortgage rates even though the Bank of England has not necessarily raised base rates.
For borrowers, this creates a confusing picture: headlines say rates are rising, yet some mortgage deals still appear relatively cheap. The reason lies in the type of mortgage product being chosen.
Why Fixed Rates Look Much Higher Than Discount Deals
Fixed-rate mortgages are priced based on future expectations. Lenders look at where markets think inflation and interest rates are heading over the next 2, 3, or 5 years. Because there is increased uncertainty, lenders are building in a safety margin — making fixed deals more expensive.
Discount mortgages, by contrast, are linked to a lender’s standard variable rate (SVR) and often offer a temporary reduction ie: -2.0% to 3.0% below that rate. They can look attractive because they are not priced on long-term swap market expectations in the same way;
The Downside is:
- They expose borrowers to future rate rises on lenders SVR rates.
The Upside is:
- Borrowers can benefit if lenders reduce their SVR rate downward with BOE downward movements. (however the lender is not obliged to reduce)
Could Fixing In Be a Risk?
Fixing your mortgage rate gives certainty, but it can also carry risk if interest rates fall in the future.
We saw something similar during the pandemic. When COVID created a global emergency, governments stepped in with huge financial support like furlough schemes, and central banks cut interest rates to historic lows to keep economies moving. Mortgage rates dropped sharply as a result.
If current uncertainty were to develop into a wider international economic crisis, something similar could happen again. No one knows for certain. Rising energy prices may push inflation higher, which would normally pressure central banks to raise rates. But if higher costs begin hurting growth too much, governments and central banks may instead decide to reduce rates to stimulate the economy.
That is why locking into a long fixed rate today could be risky: if rates fall significantly in the next year or two, borrowers tied into higher fixed deals may miss out on cheaper borrowing.
Example: If You Fix Too High and Rates Fall
Imagine you take a 5-year expat fixed mortgage today at 5.69% on a £200,000 mortgage.
Today’s best expat discount variable deal is around 4.30%.
Now suppose:
- The Bank of England cuts rates by 0.25%
- Lenders reduce their variable mortgage rates accordingly
- The discount rate falls to 4.05%
That creates a difference of:
5.69% fixed rate – 4.05% variable rate = 1.64% higher
If that gap remained for 3 years:
- 1.64% x £200,000 = £3,280 extra interest per year
- Over 3 years = £9,840 more interest paid
So while fixing protects you if rates rise, it can cost you heavily if rates move down and you are locked into a higher deal.
In summary fixing gives payment security — but in uncertain markets, certainty can come at the price of flexibility.
As an expat you may be unsure what might be possible or what your next move should be and we are on hand to help explore the options available to you.
Book a call here
Market Updates
- A world at war – still thinking of investing ? here is an objective view on the scene for investing ! get it here.
- Bank Of England rates held at 3.75% ..all the committee members agreed to hold, with expectation of a flat year read the report here.
- MTD – Making Tax Digital – becomes a reality this month April 26. Get prepared now with this podcast
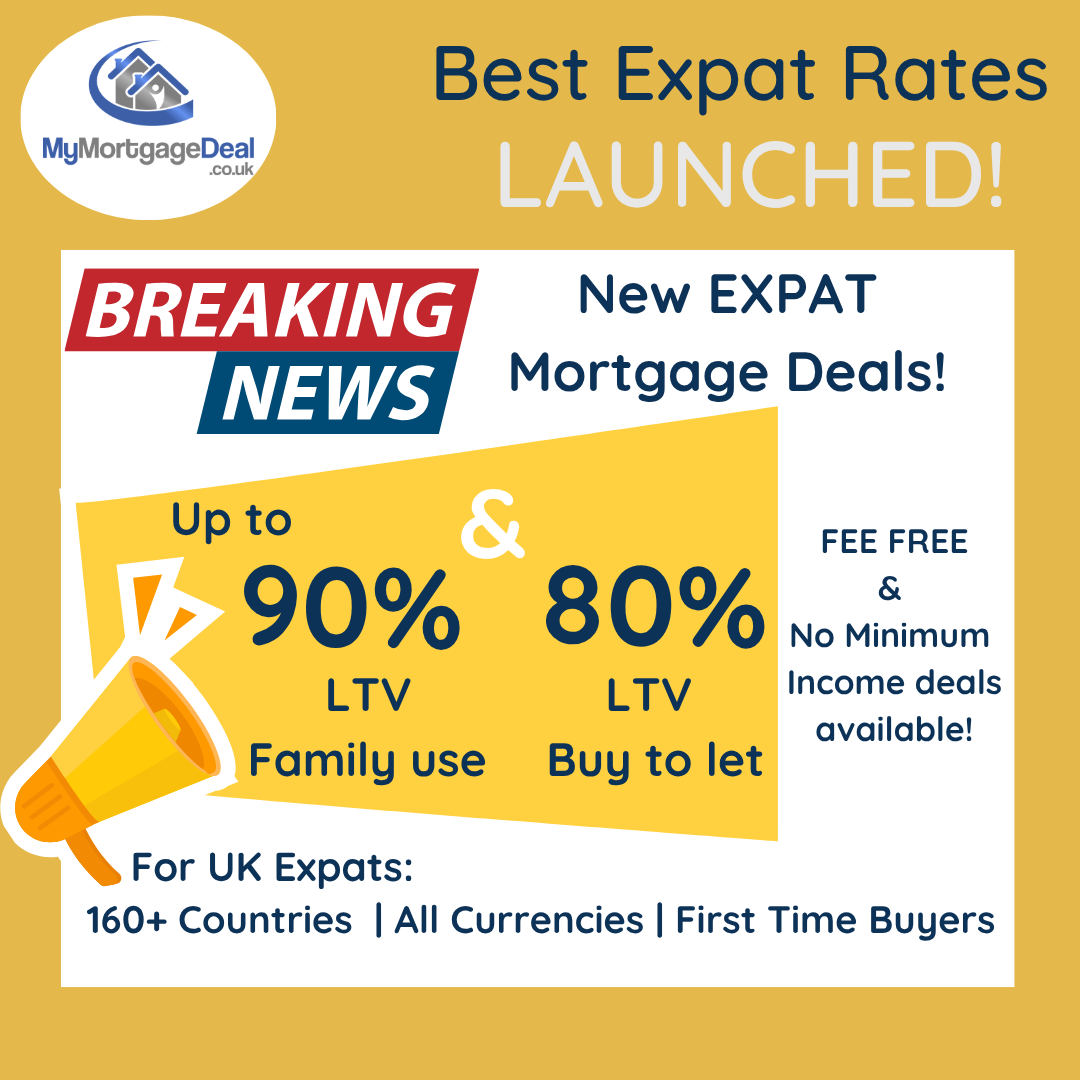
- 90% expat mortgages still being offered and with discount deals from 5.55% & fixed from 5.79% is now the time to act ? over 160+ countries accepted as the Expat country of residence.
Next Steps…
Book a Free Discovery call here & if your not sure what a discovery call is all about Ive made a series of videos on what to expect here.
A Great way to get frequent updates, hints & tips and insider industry knowledge of the complex / expat mortgage market is to join our YouTube channel here.
Our Quick 60sec Quote page allows you to obtain the latest rates to be expected and you can request a specific quote by sending an email to info@mymotgagedeal.co.uk
by admin | Mar 20, 2026 | credit reference, Expat mortgages, Mortgage rates, Re-mortgage, Releasing cash, Switch mortgages, UK mortgage, UK property
The 90 % Expat UK Mortgage & other unique expat mortgage deals…!
Get it while it lasts.. the 90% expat mortgage is still available serving UK passport holders & Irish passport holders ( with a Uk credit history) overseas working in over 150 countries:
Up to 90% LTV on a 2 yr Fixed 5.49% & Max loan £585K
Its quite a unique proposition that as an expat you can buy a home for you/ family use while working overseas in a different currency. Not many lenders are able to go to 90% and so there are some stipulations:
- Earn over £40K GBP equiv a year as a minimum
- Have a UK credit footprint
- No adverse credit in the Uk
- Employed applicants only (not self employed)
- Applies only to England/Wales
Reach out to us / book a call to explore if you fit criteria and get a free approval.
Other Unique Expat Deals:
Expat Self Build mortgages – Up to 80% of purchase price / project value. This product can be used for Ground up new builds or for Non-habitable renovation projects. The client needs to have sufficient funds to pay for each stage in advance over a 4/5 stage funds release completion process.
Expat – No Proven income Buy to let up to 85% – If you are employed / Self employed as a UK Expat and either want to buy or refinance a Buy to Let in the UK, we have some lenders that dont even ask for proof of income. So if your income varies or is on the light side, then this could be a great solution.
As an expat you may be unsure what might be possible or what your next move should be and we are on hand to help explore the options available to you.
Book a call here
Market Updates
- Get Fully prepared for the Renters Rights act – with Rob Dix ‘How to be a landlord 2nd edition’ – with now a Amazon discount ! get it here.
- Its Fast and furious now with the Middle East Chaos to remortgage ..mortgage products are expiring quicker than milk at the moment. read the report here.
- Are HMO mortgages worth re-considering ? – this report shines a light on the rising market of room rents. Get the article here
- MTD – Making Tax Digital – becomes a reality from April 26. Get prepared now with this podcast
Next Steps…
Book a Free Discovery call here & if your not sure what a discovery call is all about Ive made a series of videos on what to expect here.
A Great way to get frequent updates, hints & tips and insider industry knowledge of the complex / expat mortgage market is to join our YouTube channel here.
Our Quick 60sec Quote page allows you to obtain the latest rates to be expected and you can request a specific quote by sending an email to info@mymotgagedeal.co.uk